Barry, OppHub America Desk · · Source: yahoo-tickers-tape-movers
CoStar Group Q3 Revenue Climbs 14.1% to $952M Amid Cost Focus
If CoStar Group manages booking velocity relative to its $200 million cost-savings pipeline, watch the equity for margin expansion; otherwise, monitor booking recovery milestones.
Based on reporting from yahoo-tickers-tape-movers.
CoStar Group ($CSGP+WL) posted third-quarter revenue of $952 million, up 14.1% year-on-year, alongside a non-GAAP profit of $0.38 per share that beat analyst consensus estimates by 12%. Despite the top-line expansion, management highlighted softer-than-expected net new bookings at $37 million and announced approximately $200 million in identified expense-reduction opportunities.
Market context for this story
As of: After HoursLoading quotes…
Informational only — not investment advice. Full markets →

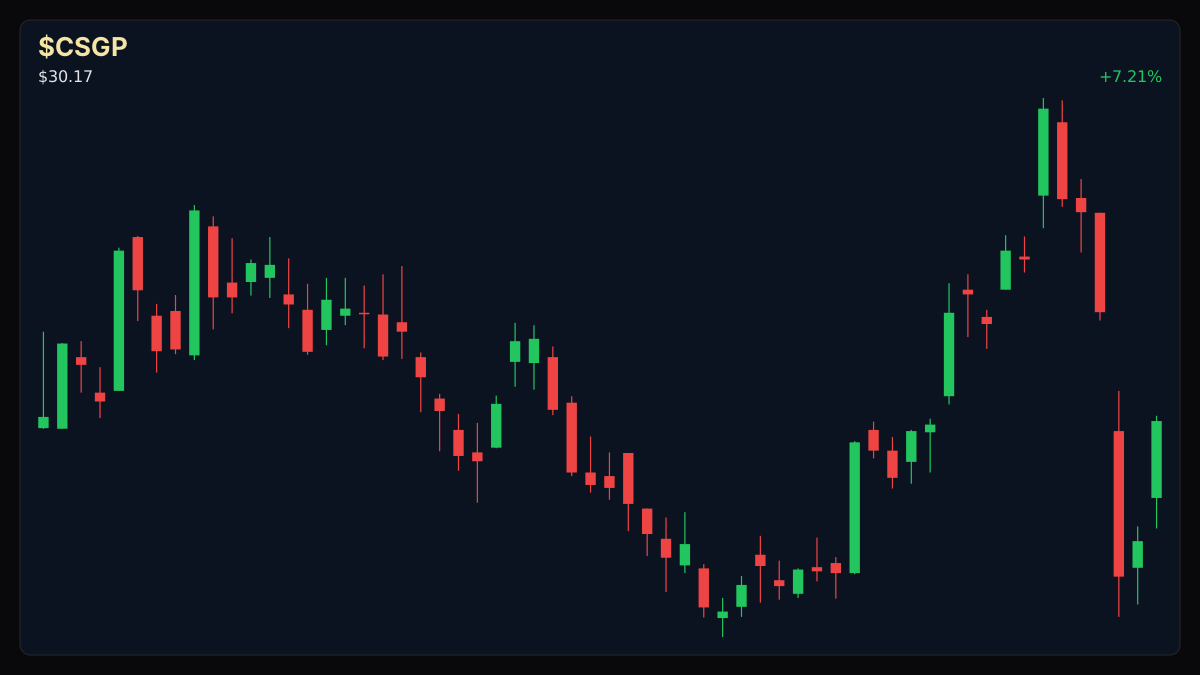
$CSGPCoStar Group
TradingView
Live chart & market data via TradingView · OppHub classroom · Delayed or exchange real-time per TradingView data agreements · Not investment advice
Educational TradingView chart — search any symbol in the widget. Confirm on /markets/CSGP. Not investment advice.
Related markets
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).
CoStar Group ($CSGP+WL) reported third-quarter revenue of $952 million, marking a 14.1% increase compared to the same period last year and exceeding consensus expectations. Non-GAAP profit landed at $0.38 per share, outpacing analyst forecasts by 12%.
### Earnings & Cost Review While revenue growth remained robust, leadership pointed to net new bookings coming in softer than anticipated at $37 million for the third quarter, alongside workforce and recruitment headwinds. In response, the company conducted a comprehensive expense review, targeting roughly $200 million in potential cost savings across procurement and operations.
### Forward Outlook Looking ahead, CoStar Group projects next quarter's revenue to reach approximately $986 million, aligning closely with existing analyst projections as product investments and cost controls shape the operational trajectory.
### Money Play If CoStar Group ($CSGP+WL) manages booking velocity relative to its $200 million cost-savings pipeline, watch the equity for margin expansion; otherwise, monitor booking recovery milestones.
Read the full story
Original reporting and related coverage — attribution links only, not paid recommendations.
Trade this story
 Robinhood
 Webull
 Tradier
 IBKR
Chart this story
 TradingView
Broker and exchange buttons use invite / refer-a-friend links (rewards may be capped). Charting links (TradingView) are partner offers that may pay OppHub America a commission at no extra cost to you.
OppSHOP
Full OppSHOP →As an Amazon Associate, OppHub America earns from qualifying purchases. Shopping here helps keep the site free — at no extra cost to you. Disclosure
OppSHOP
Related to this story
If CoStar Group manages booking velocity relative to its $200 million co
Shop related →
Investing books
Read the classics
Shop this pick →
Personal finance books
Run the household books
Shop this pick →
Trading notebooks
Write the thesis first
Shop this pick →
Monitor for charts
See every pane
Shop this pick →
Story playbook
A pre-built map of what to watch — stocks, ETFs, and educational next steps. Not personalized advice.
Snapshot date: October 30, 2026 at 7:55 PM ET
This playbook was built when the story published and is not live-updated. Prices, news, and risk can change after this date — treat it as a starting map, not a current trade ticket.
Story → money map
commercial real estate data and cost efficiency
A major real estate data company made more money than expected and beat profit goals, but new customer sign-ups slowed down. To make up for it, the company plans to cut $200 million in expenses, which investors will watch closely to see if it boosts profits.
What changed
CoStar Group beat Q3 revenue and profit estimates but revealed softer net new bookings, prompting a $200 million cost-reduction plan.
Who wins / who loses
Cost-conscious operators and margin-focused investors benefit from potential savings, while growth-oriented investors suffer from slowing booking velocity.
Time horizon
Think in terms of the next few months.
Confidence & best fit
medium confidence · Long-term investor, Active trader
Safer theme exposure (ETFs)
Baskets that own the theme without betting on one company.
Single stocks (higher risk)
Primary = closest to the story · Peers = same industry · Second-order = knock-on effects · Avoid = looks related but may be a trap
Primary
- $CSGPWatch — track, don’t rush
The main company in the story is growing revenue, but fewer new sales mean management must cut costs to keep profits looking good.
View $CSGP chart → · End-of-day delayed data
Options (education only)
No strikes or expiries — a framework for how traders might express the view. Options can expire worthless.
Beginners should skip options on this stock right now because it is unclear if cost cuts or slowing sales will drive the price.
See options-friendly brokers →Income / OppHub America angle
Not a trade tip — ways to use the insight outside the market.
- Monitor commercial real estate market health indicators and local leasing activity.
What would break this thesis
- Net new bookings accelerate significantly above expectations, or cost-savings targets are missed.
What to do next on OppHub America
Saved playbooks stay on this device for now.
Important
Not financial advice. OppHub America playbooks are educational market maps only — not recommendations to buy, sell, or hold any security. Markets move fast; information can be wrong or outdated. Trade and invest at your own risk. Do your own research or consult a licensed advisor.
Based on reporting from yahoo-tickers-tape-movers.
Informational and educational only — not investment, financial, or legal advice. Disclosure
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).