Barry, OppHub America Desk · · Source: yahoo-tickers-rotation
Energy Transfer ET Yield & Tax Placement: Roth IRA Advantages
If holding Energy Transfer , review account placement to assess whether moving ordinary-income distributions into a Roth preserves annual yield by avoiding marginal tax rates up to 37%.
Based on reporting from yahoo-tickers-rotation.
Where investors park high-yield ordinary-income assets like Energy Transfer LP ($ET+WL) dictates annual tax drag, as distributions face rates up to 37% in taxable accounts. Moving a $500,000 position yielding 8% into a Roth IRA avoids thousands in yearly IRS liabilities.
Market context for this story
As of: WeekendLoading quotes…
Informational only — not investment advice. Full markets →


$ETEnergy Transfer LP
TradingView
Live chart & market data via TradingView · OppHub classroom · Delayed or exchange real-time per TradingView data agreements · Not investment advice
Educational TradingView chart — search any symbol in the widget. Confirm on /markets/ET and related $HYG, $MO. Not investment advice.
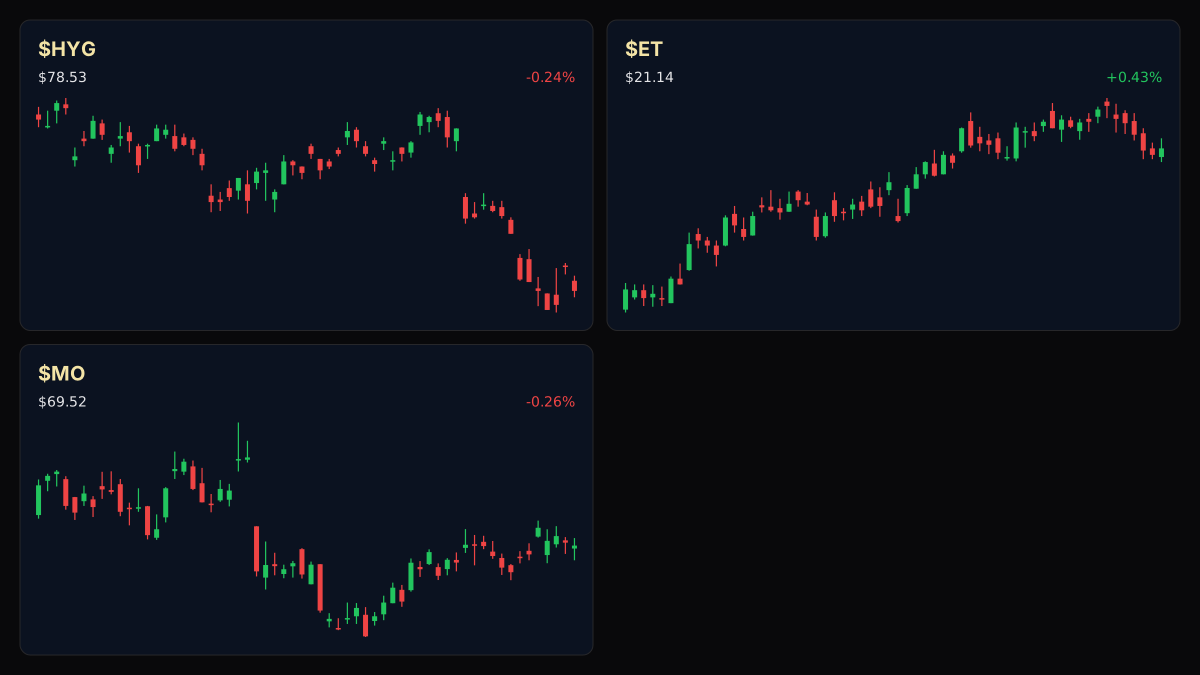
Related markets
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).
Where investors park high-yield ordinary-income assets like Energy Transfer LP ($ET+WL) dictates annual tax drag, as distributions face rates up to 37% in taxable accounts compared to tax-free compounding inside a Roth IRA.
### Money Play - If managing ordinary-income distributions from MLP assets like Energy Transfer LP ($ET+WL), consider evaluating tax-advantaged account placement such as a Roth IRA to eliminate annual tax drag up to the 37% marginal bracket.
## Catalyst Analysis: Tax Drag and Distribution Placement - Ordinary Income Tax Rate: Up to 37% marginal rate applied to REIT and MLP distributions in taxable accounts. - Tax Delta on Position: A $500,000 position yielding 8% generates $40,000 in annual income, producing $30,400 after tax at the 24% bracket versus the full $40,000 inside a Roth IRA.
Master Limited Partnerships (MLPs) and Real Estate Investment Trusts (REITs) distribute income taxed at ordinary rates rather than favorable long-term capital gains rates. At the 24% federal bracket, a $50,000 stream of ordinary dividend income results in roughly $12,000 paid to the IRS annually within a taxable brokerage account.
Placing these yield-heavy vehicles inside tax-sheltered structures shields the cash flow entirely. The resulting $9,600 annual difference on an 8% yielding $500,000 position allows reinvested capital to compound without intermediary tax friction. For single filers and joint filers navigating marginal rates spanning up to the 37% top tier, account architecture remains as critical as asset selection.
Read the full story
Original reporting and related coverage — attribution links only, not paid recommendations.
Trade this story
 Robinhood
 Webull
 Tradier
 IBKR
Chart this story
 TradingView
Broker and exchange buttons use invite / refer-a-friend links (rewards may be capped). Charting links (TradingView) are partner offers that may pay OppHub America a commission at no extra cost to you.
OppSHOP
Full OppSHOP →As an Amazon Associate, OppHub America earns from qualifying purchases. Shopping here helps keep the site free — at no extra cost to you. Disclosure
OppSHOP
Related to this story
If holding Energy Transfer , review account placement to assess whether
Shop related →
Investing books
Read the classics
Shop this pick →
Personal finance books
Run the household books
Shop this pick →
Trading notebooks
Write the thesis first
Shop this pick →
Monitor for charts
See every pane
Shop this pick →
Story playbook
A pre-built map of what to watch — stocks, ETFs, and educational next steps. Not personalized advice.
Snapshot date: September 19, 2026 at 9:46 AM ET
This playbook was built when the story published and is not live-updated. Prices, news, and risk can change after this date — treat it as a starting map, not a current trade ticket.
Story → money map
tax-advantaged investing
High-paying investments can get hit with heavy taxes when held in standard accounts. Moving them into a special tax-free retirement account lets you keep all your cash and grow your money faster.
What changed
Financial analysts are highlighting the substantial tax drag of holding Master Limited Partnerships (MLPs) in taxable accounts versus tax-advantaged vehicles like Roth IRAs.
Who wins / who loses
Long-term investors utilizing tax-sheltered accounts benefit from higher compounding returns, while passive holders in taxable accounts lose up to 37% of their annual distributions to taxes.
Time horizon
Think in terms of the next few months.
Confidence & best fit
high confidence · Long-term investor
Safer theme exposure (ETFs)
Baskets that own the theme without betting on one company.
Single stocks (higher risk)
Primary = closest to the story · Peers = same industry · Second-order = knock-on effects · Avoid = looks related but may be a trap
Primary
- $ETWatch — track, don’t rush
This company pays out a lot of cash, which causes big tax bills unless you hold it in the right type of account.
View $ET chart → · End-of-day delayed data
Options (education only)
No strikes or expiries — a framework for how traders might express the view. Options can expire worthless.
Beginners should skip options for this strategy and focus purely on choosing the right type of retirement account.
See options-friendly brokers →Income / OppHub America angle
Not a trade tip — ways to use the insight outside the market.
- Reviewing all ordinary-income yielding assets across taxable and tax-advantaged accounts to minimize overall IRS drag.
What would break this thesis
- Changes to US tax code regarding MLP distribution taxation or Roth IRA contribution limits.
What to do next on OppHub America
Saved playbooks stay on this device for now.
Important
Not financial advice. OppHub America playbooks are educational market maps only — not recommendations to buy, sell, or hold any security. Markets move fast; information can be wrong or outdated. Trade and invest at your own risk. Do your own research or consult a licensed advisor.
Based on reporting from yahoo-tickers-rotation.
Informational and educational only — not investment, financial, or legal advice. Disclosure
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).