OppHub America Desk · · Source: yahoo-tickers-tape-movers
Marriott Valuation vs. Booking Holdings: Multiple and Growth
If lodging sector valuations remain elevated despite moderating fourth-quarter room night forecasts, watch and for relative performance divergence based on operating margin strength and net debt levels. Investors tracking broader consumer discretionary exposure can monitor for sector-wide sentiment shifts, alongside for broader market context.
Based on reporting from yahoo-tickers-tape-movers.
Marriott International trades at a 40.7x earnings multiple compared to 15.4x for Booking Holdings, prompting investors to weigh Marriott's accelerating revenue per room against Booking's wider margins and stronger cash reserves.
Market context for this story
As of: WeekendLoading quotes…
Informational only — not investment advice. Full markets →


$SPYSPDR S&P 500 ETF
TradingView
Live chart & market data via TradingView · OppHub classroom · Delayed or exchange real-time per TradingView data agreements · Not investment advice
$BKNGBooking Holdings
TradingView
Live chart & market data via TradingView · OppHub classroom · Delayed or exchange real-time per TradingView data agreements · Not investment advice
Educational TradingView charts — search any symbol in the widget. Confirm on /markets/SPY and related $BKNG, $MAR, $XLY. Not investment advice.
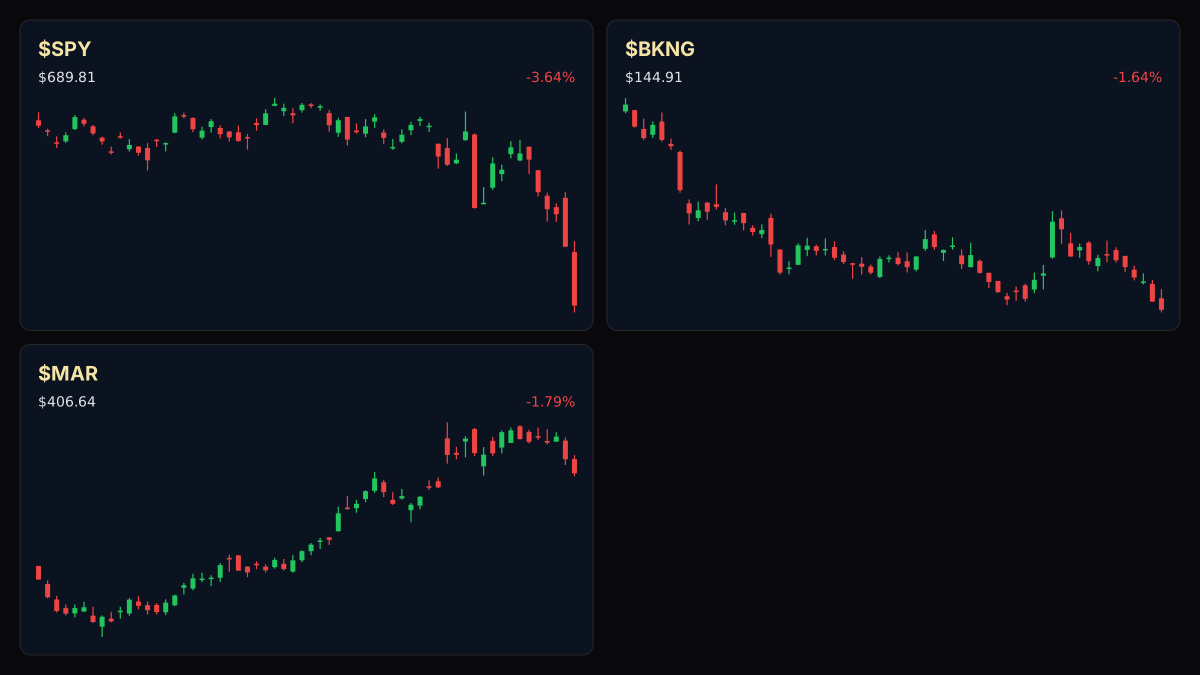
Related markets
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).
Marriott International (NASDAQ: MAR) and Booking Holdings (NASDAQ: BKNG) present divergent valuation profiles and balance sheet structures as investors evaluate travel demand persistence through late 2026 and into 2027. Marriott shares trade at 40.7 times earnings, while Booking Holdings commands a 15.4x multiple, reflecting different capital structures, operating margins, and growth trajectories across the lodging and online travel agency sectors.
### Valuation and Financial Comparison
Marriott reported fiscal third-quarter 2026 revenue growth of 8.0% year-over-year, following a 3.7% increase in the same period of 2025, with management citing a 14% rise in gross fee revenues driven by higher revenue per available room (RevPAR), room additions, and co-branded credit card fees. On November 2, Marriott raised its full-year 2026 RevPAR growth forecast to a midpoint of 4.8%, up from 3.3% in August, while noting that fourth-quarter global RevPAR growth is expected to moderate to between 4.5% and 5%.
In contrast, Booking Holdings reported third-quarter room night growth of 7% but anticipates fourth-quarter growth slowing to a range of 1% to 3%, citing persistent Middle East conflict impacts on travel demand. Over the twelve months ending September 30, Booking generated revenue growth of 8.0% (down from 13.0% a year earlier) compared to Marriott's 5.8% revenue growth. Booking also posted an operating margin of 32.8% over the same period, outpacing Marriott's 15.9% operating margin.
### Balance Sheet and Capital Structure
Balance sheet metrics highlight stark differences in liquidity between the two operators. As of September 30, Marriott carried $17.7 billion in total debt against $0.45 billion in cash and short-term investments, resulting in net debt of $17.2 billion. Booking Holdings held $20.6 billion in total debt alongside $15.8 billion in cash and short-term investments, leaving net debt at $4.76 billion and providing significantly larger liquidity reserves to navigate potential travel sector softening.
### Money Play
If lodging sector valuations remain elevated despite moderating fourth-quarter room night forecasts, watch $MAR+WL and $BKNG+WL for relative performance divergence based on operating margin strength and net debt levels. Investors tracking broader consumer discretionary exposure can monitor $XLY+WL for sector-wide sentiment shifts, alongside $SPY+WL for broader market context.
### Tape / Session Read
Broad market and sector ETFs reflected slight compression during the recent session, with $SPY+WL closing at $730.20 (-0.31% on 1.03x relative volume), $XLY+WL settling at $117.58 (-0.05% on 1.21x volume), and $XLV+WL trading at $184.80 (-0.06% on 1.37x volume).
### Why This Lane Matters
The valuation spread between asset-light hospitality franchisers and digital booking platforms illustrates how markets price recurring fee revenue versus high-margin transactional volume during periods of moderating travel growth.
### Related Names
- $BKNG+WL - $SPY+WL - $XLY+WL
## $SPY+WL Technical Analysis & Key Risk Watch — S&P 500 ETF Price Levels and RSI Stance
Read the full story
Original reporting and related coverage — attribution links only, not paid recommendations.
Trade this story
 Robinhood
 Webull
 Tradier
 IBKR
Chart this story
 TradingView
Broker and exchange buttons use invite / refer-a-friend links (rewards may be capped). Charting links (TradingView) are partner offers that may pay OppHub America a commission at no extra cost to you.
OppSHOP
Full OppSHOP →As an Amazon Associate, OppHub America earns from qualifying purchases. Shopping here helps keep the site free — at no extra cost to you. Disclosure
OppSHOP
Related to this story
If lodging sector valuations remain elevated despite moderating fourth-q
Shop related →
Investing books
Read the classics
Shop this pick →
Personal finance books
Run the household books
Shop this pick →
Trading notebooks
Write the thesis first
Shop this pick →
Monitor for charts
See every pane
Shop this pick →
Based on reporting from yahoo-tickers-tape-movers.
Informational and educational only — not investment, financial, or legal advice. Disclosure
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).