Barry, OppHub America Desk · · Source: seeking-alpha
Regency Centers Preferred Shares Downgraded to Hold on Spreads
For investors tracking Regency Centers , preferred issues and yield 7.04% to 7.10%, offering solid capital preservation but reduced relative value following recent spread compression.
Based on reporting from seeking-alpha.
On Saturday, September 26, 2026, Regency Centers Corporation (NASDAQ: REG) saw its preferred shares downgraded from buy to hold as yield spreads over Treasuries compressed. While the underlying balance sheet remains investment-grade, current pricing no longer offers sector-beating income advantages for income-focused portfolios.
Market context for this story
As of: WeekendLoading quotes…
Informational only — not investment advice. Full markets →


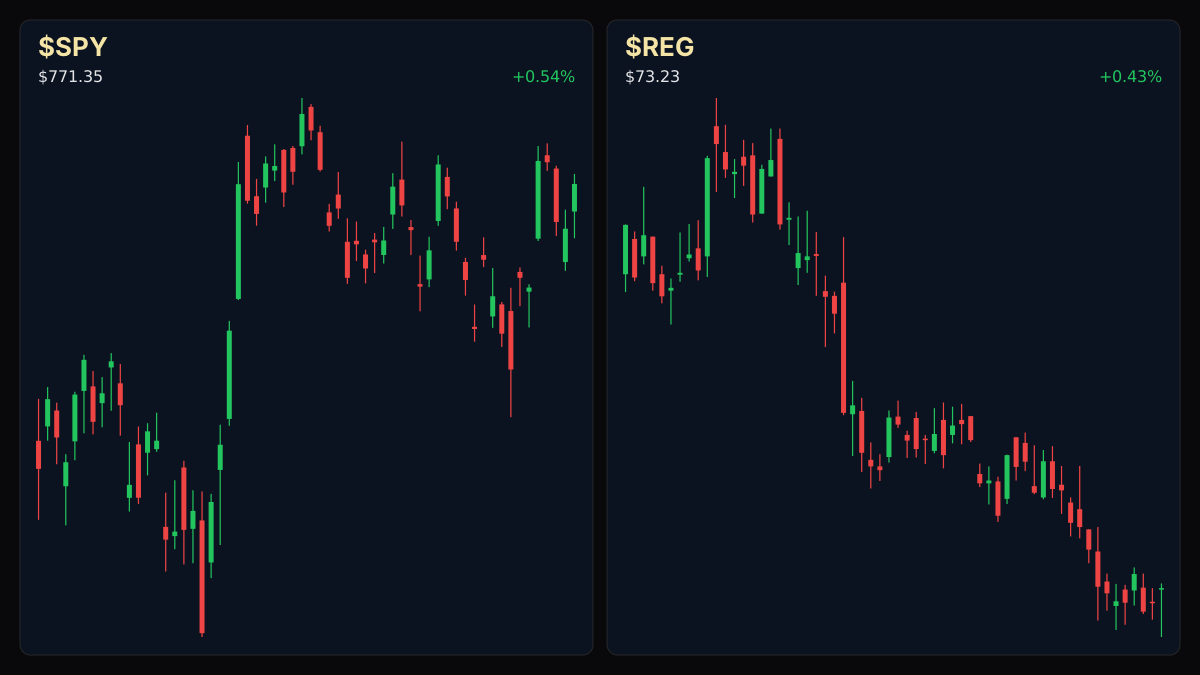
$SPYSPDR S&P 500 ETF
TradingView
Live chart & market data via TradingView · OppHub classroom · Delayed or exchange real-time per TradingView data agreements · Not investment advice
Educational TradingView chart — search any symbol in the widget. Confirm on /markets/SPY and related $REG, $VNQ. Not investment advice.
Related markets
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).
Regency Centers Corporation (NASDAQ: REG) preferred series (REGCO, REGCP) shifted to a hold rating on Saturday, September 26, 2026, following yield compression relative to comparable Treasury benchmarks.
### Money Play - For portfolios tracking Regency Centers (NASDAQ: REG), the preferred shares (REGCO, REGCP) currently yield between 7.04% and 7.10%, offering stable capital preservation but diminished relative value against broader REIT yield alternatives.
## Catalyst Analysis: Preferred Valuation & Spread Compression - Yield / Spread: REGCO and REGCP yields range from 7.04% to 7.10%, with narrowing spreads over Treasuries driving the rating adjustment. - Balance Sheet Quality: Moody's A3 and S&P A- credit ratings underscore a solid financial position, characterized by high unencumbered assets and conservative leverage. - Portfolio Positioning: Price stability during prior sector volatility preserved principal, yet the erosion of the relative yield premium prompted a reassessment from buy to hold for income allocators.
## $REG+WL Technical Analysis & Key Risk Watch
10.85 · R1 ## $REG+WL Technical Analysis & Key Risk Watch 09.19 · last ## $REG+WL Technical Analysis & Key Risk Watch 08.60 · S1 ## $REG+WL Technical Analysis & Key Risk Watch 08.30 · S2 ## $REG+WL Technical Analysis & Key Risk Watch 04.41.
Market positioning for income vehicles requires monitoring duration risk and macro spread dynamics. While common equity maintains robust institutional sponsorship backed by high-grade real estate assets, preferred income instruments face diminishing relative alpha as peer yields catch up to historical benchmarks.
### Sector Ripple / Impact on Real Estate & REITs - Real Estate Investment Trusts (VNQ): Spread narrowing across high-grade REIT preferreds signals broader normalization in fixed-income real estate yields, affecting relative value models across retail-focused operators.
Read the full story
Original reporting and related coverage — attribution links only, not paid recommendations.
Trade this story
 Robinhood
 Webull
 Tradier
 IBKR
Chart this story
 TradingView
Broker and exchange buttons use invite / refer-a-friend links (rewards may be capped). Charting links (TradingView) are partner offers that may pay OppHub America a commission at no extra cost to you.
OppSHOP
Full OppSHOP →As an Amazon Associate, OppHub America earns from qualifying purchases. Shopping here helps keep the site free — at no extra cost to you. Disclosure
OppSHOP
Related to this story
For investors tracking Regency Centers , preferred issues and yield 7.04
Shop related →
Investing books
Read the classics
Shop this pick →
Personal finance books
Run the household books
Shop this pick →
Trading notebooks
Write the thesis first
Shop this pick →
Monitor for charts
See every pane
Shop this pick →
Story playbook
A pre-built map of what to watch — stocks, ETFs, and educational next steps. Not personalized advice.
Snapshot date: September 26, 2026 at 12:17 PM ET
This playbook was built when the story published and is not live-updated. Prices, news, and risk can change after this date — treat it as a starting map, not a current trade ticket.
Story → money map
REIT preferred shares
A company that owns shopping centers has preferred stock that pays a steady dividend, but experts now say the price is too high compared to safe government bonds. While you still get a decent payout, new buyers aren't getting a special bargain anymore.
What changed
Preferred shares of Regency Centers were downgraded to hold following yield spread compression relative to Treasuries.
Who wins / who loses
Broad Treasury holders and alternative high-yield income vehicles benefit from capital rotation, while income-seeking preferred stock buyers face diminished relative value.
Time horizon
Think in terms of the next few months.
Confidence & best fit
medium confidence · Long-term investor
Safer theme exposure (ETFs)
Baskets that own the theme without betting on one company.
Single stocks (higher risk)
Primary = closest to the story · Peers = same industry · Second-order = knock-on effects · Avoid = looks related but may be a trap
Primary
- $REGWatch — track, don’t rush
The main company's special dividend shares are less attractive now because safer government bonds pay almost as much.
View $REG chart → · End-of-day delayed data
Peer
- $KIMWatch — track, don’t rush
Similar shopping center companies might see their dividend yields re-evaluated by the market too.
View $KIM chart → · End-of-day delayed data
Second-order
- $SPGWatch — track, don’t rush
Big mall owners act as a yardstick for whether real estate dividend stocks are priced fairly.
View $SPG chart → · End-of-day delayed data
Options (education only)
No strikes or expiries — a framework for how traders might express the view. Options can expire worthless.
Options are not recommended here because these special dividend shares move very slowly, much like bonds.
See options-friendly brokers →Income / OppHub America angle
Not a trade tip — ways to use the insight outside the market.
- Compare current preferred yields against short-term Treasury bills for risk-adjusted return advantages.
What would break this thesis
- A sudden widening of credit spreads or a significant drop in benchmark interest rates that re-establishes attractive yield premiums.
What to do next on OppHub America
Saved playbooks stay on this device for now.
Important
Not financial advice. OppHub America playbooks are educational market maps only — not recommendations to buy, sell, or hold any security. Markets move fast; information can be wrong or outdated. Trade and invest at your own risk. Do your own research or consult a licensed advisor.
Based on reporting from seeking-alpha.
Informational and educational only — not investment, financial, or legal advice. Disclosure
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).