Barry, OppHub America Desk · · Source: seeking-alpha
Western Midstream (WES) Upgraded: 9% Yield & 2027 Outlook
If evaluating midstream cash flows, watch Western Midstream as projected 2027 E of $3.2 billion and a $0.96 quarterly distribution reinforce a fair value estimate of $51 per unit.
Based on reporting from seeking-alpha.
Western Midstream Partners (WES) has been upgraded to a strong buy, underpinned by a 9% yield and projected 2027 EBITDA of $3.2 billion. Investors are evaluating the firm's controlled leverage and upcoming asset milestones ahead of 2027 distribution coverage.
Market context for this story
As of: WeekendLoading quotes…
Informational only — not investment advice. Full markets →


$WESWestern Midstream
TradingView
Live chart & market data via TradingView · OppHub classroom · Delayed or exchange real-time per TradingView data agreements · Not investment advice
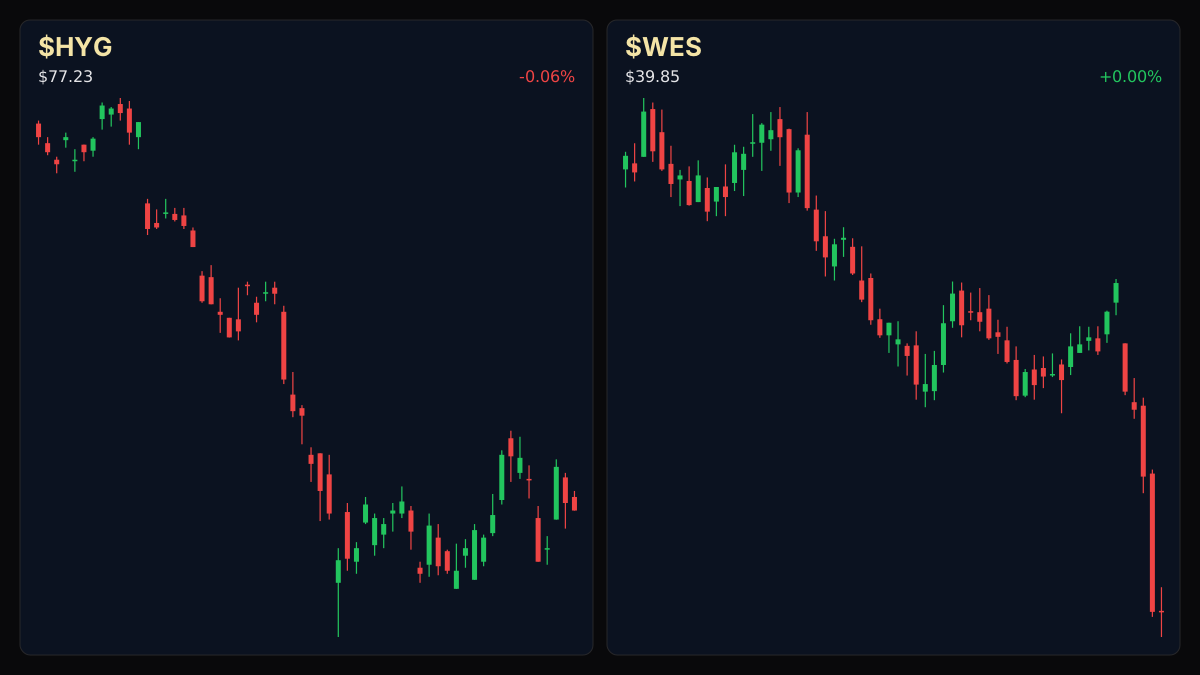
Educational TradingView chart — search any symbol in the widget. Confirm on /markets/WES and related $HYG. Not investment advice.
Related markets
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).
Western Midstream Partners (NYSE: WES) is drawing fresh institutional attention following a rating upgrade highlighting robust cash flow generation and a 9% yield expected through 2027.
### Money Play - If seeking high-yield infrastructure exposure, watch Western Midstream ($WES+WL) as projected 2027 distributions of $0.96 per quarter and 1.44x coverage support a $51 per unit fair value target.
## Catalyst Analysis: Growth Outlook and Cash Flow Projections - Revenue / EPS: Financial metrics focus on projected 2027 operational estimates rather than quarterly earnings beats. - Forward Guidance: Projected EBITDA is pegged at $3.2 billion alongside distributable cash flow (DCF) of $2.3 billion for 2027, backed by major expansions including the Pathfinder Pipeline and North Loving II.
The valuation framework centers on disciplined capital allocation and diversified operations across the Delaware Basin. With a fair value assessment of $51 per unit and a projected quarterly distribution of $0.96, the partnership maintains a 1.44x coverage ratio. Midstream operators with controlled leverage metrics continue to attract yield-focused capital as asset expansions move toward completion.
## $WES+WL Technical Analysis & Key Risk Watch
Technical positioning for $WES+WL benefits from positive sentiment in midstream energy assets, supported by stable distribution coverage and multi-year pipeline integration timelines. Key risk factors remain tied to broader commodity price fluctuations and execution timelines on upcoming Delaware Basin infrastructure projects.
### Sector Ripple / Impact on Energy Infrastructure - Western Midstream ($WES+WL)
Read the full story
Original reporting and related coverage — attribution links only, not paid recommendations.
Trade this story
 Robinhood
 Webull
 Tradier
 IBKR
Chart this story
 TradingView
Broker and exchange buttons use invite / refer-a-friend links (rewards may be capped). Charting links (TradingView) are partner offers that may pay OppHub America a commission at no extra cost to you.
OppSHOP
Full OppSHOP →As an Amazon Associate, OppHub America earns from qualifying purchases. Shopping here helps keep the site free — at no extra cost to you. Disclosure

OppSHOP
Related to this story
If evaluating midstream cash flows, watch Western Midstream as projected
Shop related →

Investing books
Read the classics
Shop this pick →

Personal finance books
Run the household books
Shop this pick →

Trading notebooks
Write the thesis first
Shop this pick →

Monitor for charts
See every pane
Shop this pick →
Story playbook
A pre-built map of what to watch — stocks, ETFs, and educational next steps. Not personalized advice.
Snapshot date: November 7, 2026 at 10:31 PM ET
This playbook was built when the story published and is not live-updated. Prices, news, and risk can change after this date — treat it as a starting map, not a current trade ticket.
Story → money map
midstream energy yield
A company that moves oil and gas got a positive rating because it pays a high 9% dividend to investors. People who care about steady income are paying attention because the company expects to make a lot of money over the next few years.
What changed
Western Midstream was upgraded to a strong buy rating based on solid long-term cash flow projections and a 9% yield.
Who wins / who loses
High-yield income investors and midstream pipeline operators benefit, while firms struggling with high debt leverage or declining energy volumes lag.
Time horizon
Think in terms of the next few months.
Confidence & best fit
medium confidence · Long-term investor, Side income / builder
Safer theme exposure (ETFs)
Baskets that own the theme without betting on one company.
- $AMLP — A basket of many pipeline companies so you don't have to risk your money on just one business.
- $MLPA — Another diversified fund focused on companies that transport oil and gas.
Single stocks (higher risk)
Primary = closest to the story · Peers = same industry · Second-order = knock-on effects · Avoid = looks related but may be a trap
Primary
- $WESWatch — track, don’t rush
This is the main company in the news, and analysts think its steady cash payments make it worth watching.
View $WES chart → · End-of-day delayed data
Peer
- $EPDWatch — track, don’t rush
A similar, well-known pipeline company that also pays investors a regular cash return.
View $EPD chart → · End-of-day delayed data
Second-order
- $KMIWatch — track, don’t rush
Another large pipeline operator that tends to move up or down when the overall energy transportation sector gets attention.
View $KMI chart → · End-of-day delayed data
Options (education only)
No strikes or expiries — a framework for how traders might express the view. Options can expire worthless.
Direction: bullish · Style: Covered-call income (only if you already own shares) · Level: intermediate
Beginners should skip options; just collect the regular cash dividend if you own the units.
Income / OppHub America angle
Not a trade tip — ways to use the insight outside the market.
- Evaluate local industrial real estate or service providers supporting Delaware Basin pipeline expansions.
What would break this thesis
- A sharp drop in crude oil and natural gas production volumes in the Delaware Basin.
- Unexpected cuts to distribution coverage or rising corporate leverage.
What to do next on OppHub America
Saved playbooks stay on this device for now.
Important
Not financial advice. OppHub America playbooks are educational market maps only — not recommendations to buy, sell, or hold any security. Markets move fast; information can be wrong or outdated. Trade and invest at your own risk. Do your own research or consult a licensed advisor.
Based on reporting from seeking-alpha.
Informational and educational only — not investment, financial, or legal advice. Disclosure
Shares a vertical MP4 loop to your phone's camera roll or app share sheet (Instagram, TikTok, Facebook Reels).